Requirements and documents to start accepting card payments
Onboarding is the registration and document verification process that every merchant must complete before accepting card payments through PayOk. It answers a regulatory obligation, so PayOk applies the KYC (Know Your Customer) and AML/CFT (Anti-Money Laundering and Counter-Terrorist Financing) protocols required by current legislation.
The purpose is twofold. On one hand, it protects your business and your customers from fraud. On the other, it guarantees that the whole payment chain operates within the European and Spanish legal framework.
How onboarding works at PayOk
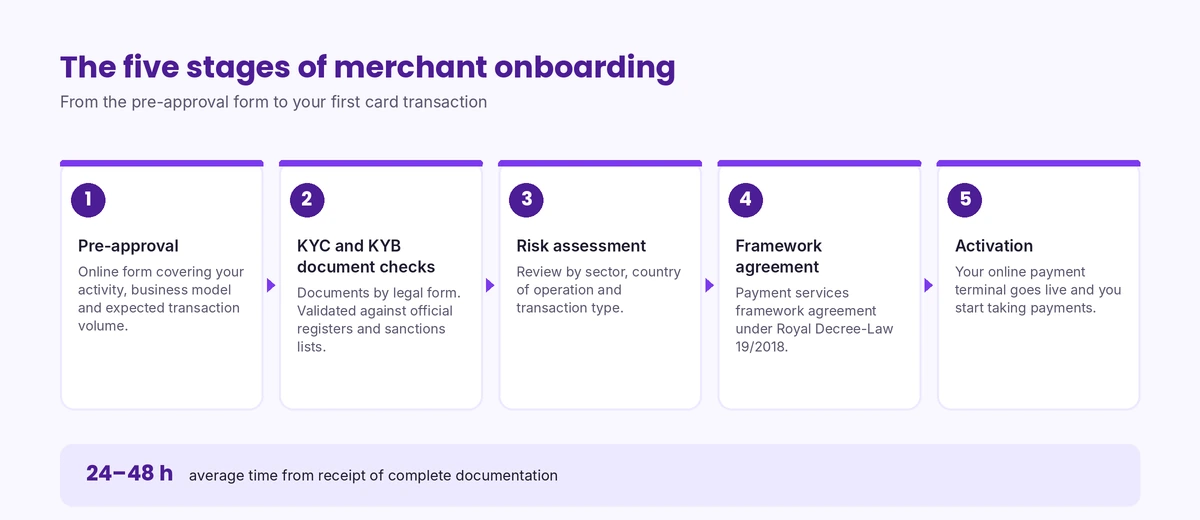
The registration process is split into stages designed to be quick without compromising regulatory compliance:
- Pre-approval. You complete the online form, where we review your commercial activity, business model and expected transaction volume.
- Document verification (KYC/KYB). You provide supporting documents according to your legal structure (sole proprietor or company). PayOk validates that the documents are authentic and cross-checks the data against official registers and international sanctions lists.
- Risk assessment. We assess the merchant risk profile by sector of activity, country of operation and transaction type. Merchants in regulated or high-risk sectors may be asked for additional documents.
- Framework agreement. The relationship is formalised through the payment services framework agreement, under Royal Decree-Law 19/2018 on payment services.
- Activation. Once all documents are validated, your online payment terminal goes live and you can start processing transactions.
Onboarding at PayOk is designed to be completed in an average of 24 to 48 hours from receipt of all correct documentation. Document verification is carried out manually and with OCR, biometrics and automated cross-checks against official databases.
Documents required by legal structure
Document requirements vary depending on whether you operate as an individual (sole proprietor, autónomo) or as a legal entity (company). This distinction follows article 4 of Law 10/2010 and Royal Decree 304/2014, which set customer due diligence obligations proportionate to risk.
| Document | Sole proprietor | Company |
|---|---|---|
| Online pre-approval form | ✓ | ✓ |
| Valid DNI or NIE (front and back, in colour, high resolution) | ✓ | Beneficial owners (UBO, >25 %) and representatives only |
| Tax registration (Form 036/037) | ✓ | ✓ |
| Latest social security receipt or tax return | ✓ | Not applicable |
| Deed of incorporation filed with the Commercial Registry | Not applicable | ✓ |
| Declaration of beneficial ownership (KYB protocol) | Not applicable | ✓ |
| Signed ownership chart (complex structures) | Not applicable | If applicable |
| Power of attorney and current certificate of office | Not applicable | If there are representatives |
| Bank account ownership certificate (less than 3 months old) | ✓ | ✓ |
| Declaration of economic activity and politically exposed person (PEP) | ✓ | ✓ |
| PayOk payment services framework agreement | ✓ | ✓ |
Regulatory framework and applicable security measures
Every onboarding requirement has a concrete legal basis. This is not unnecessary paperwork, but strict compliance with the regulatory framework that applies to payment institutions in Spain:
- Law 10/2010, of 28 April. Sets the obligations of formal customer identification, verification of the beneficial owner and classification by risk level. Article 7.3 establishes that a business relationship may only be refused on an individual basis, when the customer prevents the application of the due diligence measures appropriate to their risk profile.
- Royal Decree 304/2014. Develops the record-keeping obligations (10 years minimum), the simplified and enhanced due diligence procedures, and the reporting protocols to SEPBLAC.
- Royal Decree-Law 19/2018. Transposes the PSD2 Directive into Spanish law and regulates payment services framework agreements, transparency obligations and user rights.
- EBA Guidelines EBA/GL/2021/02 and EBA/GL/2024/01. Set the risk factors that institutions must assess in every business relationship, including sector of activity, ownership structure and source of funds.
For merchants, this means the documents requested during onboarding are not a courtesy formality. They are what allows PayOk to operate within the law, protect your business from fraudulent chargebacks and keep your payment account active without interruptions.
What you gain from a thorough onboarding
- Fraud protection. Document verification and upfront risk analysis filter out potentially fraudulent activity before it reaches your account.
- Operational continuity. A properly verified merchant is far less likely to face blocks, withheld funds or account closure for regulatory non-compliance.
- Access to better terms. Low-risk merchants backed by complete documentation can obtain more competitive fees and shorter settlement times.
- Compliance without friction. We combine manual review with OCR and automated validation, which cuts registration time without giving up regulatory rigour.
Already have your documents ready? Complete the pre-approval form at sign up. If your case has any particularities, write to us from contact and we will tell you exactly what you need before you start.
Laws and regulations:
- Law 10/2010, of 28 April, on the prevention of money laundering and terrorist financing.
- Royal Decree 304/2014, of 5 May, Regulation implementing Law 10/2010.
- Royal Decree-Law 19/2018, of 23 November, on payment services.
Recommended reading:
Leave a Comment